
Are you a first-time buyer?
The short version
You may count as a first-time buyer even if you have owned a home before. For most programs, it means you have not owned a home in the past 3 years.
Here is what it changes:
- Conventional down payment. You can put 3% down instead of 5%, as long as one borrower is a first-time buyer. HomeReady and Home Possible offer 3% down to anyone under the income limit.
- A homebuyer class. If everyone on a HomeReady loan, or on any conventional loan with less than 5% down, is a first-time buyer, one of you must take a course before closing. CHFA requires a class for all its loans.
- Assistance. Some assistance is aimed at first-time and first-generation buyers.
FHA, VA and USDA loans do not depend on first-time status. Being a first-time buyer also does not change how lenders review your income or credit.
Down payment assistance in Southwest Colorado comes from CHFA and from local programs such as HomesFund in Durango. Most of it is a loan secured by a second lien on your home, repaid when you sell or refinance, and only some of it is a grant. Before you apply for any assistance, we show you each option with and without it, so you know what the assistance costs and what you would owe.
Go deeper
Who counts
The rules differ slightly by program:
- HUD's definition, used by many assistance programs: no ownership of a principal residence in the past three years. A single parent or displaced homemaker who only owned with a former spouse can also qualify.
- Fannie Mae and Freddie Mac: no ownership in any residential property, including a rental, in the past three years, and you will live in the home.
This means someone who rents their own home but owns a rental house may qualify for some programs and not others. For conventional 3% down, only one borrower needs to qualify.
Homebuyer education
A homebuyer class covers budgeting, credit, the loan process and life after closing. Many are online and self-paced, and others are in person. Most take from a few hours to a full day.
Fannie Mae and Freddie Mac accept courses that meet national or HUD standards, including Freddie Mac's CreditSmart. CHFA requires its own approved class.
It is best to take the class early. It is more useful before you shop than in the week before closing, and the certificate must be in your file before you close.
Help aimed at first-time buyers
- CHFA: open to first-time and repeat buyers within its income limits, with down payment assistance and programs for first-generation buyers. See down payment assistance.
- Local programs such as HomesFund: down payment loans in Southwest Colorado, usually secured by a second lien and repaid when you sell or refinance, and only sometimes a grant. We compare your options with and without them before anyone applies.
- HomeReady and Home Possible: 3% down and reduced mortgage insurance for incomes up to 80% of the area median.
- Freddie Mac HomeOne: 3% down for first-time buyers, with no income limit.
See it with your numbers
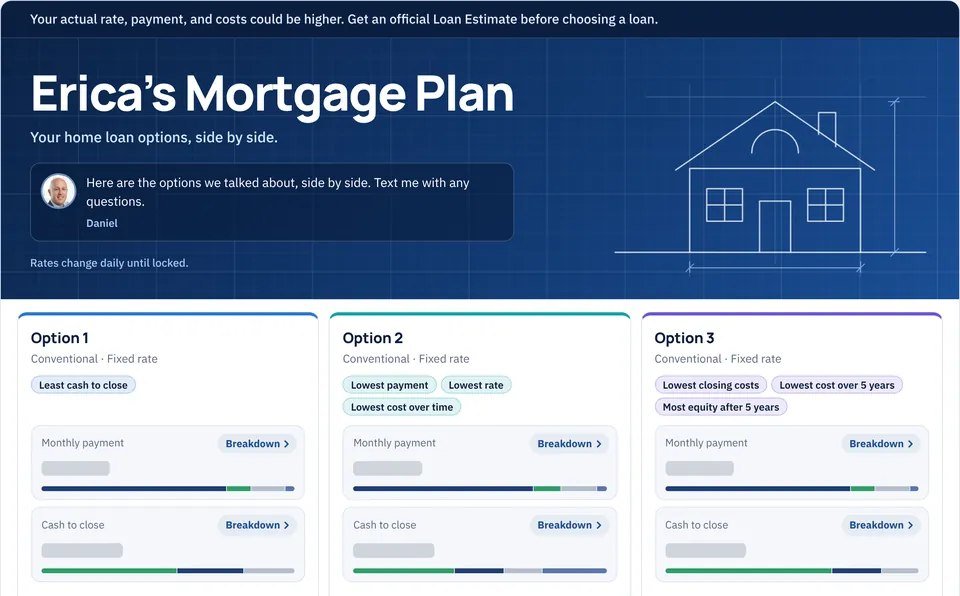
Your Mortgage Plan shows the payment and cash to close for each option you qualify for, including any low-down-payment choices.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Stage 2: What can I get?The four main loan typesConventional, FHA, VA and USDA loans differ in down payment, mortgage insurance and credit. If you qualify for VA, it is often the best of the four.Read the lessonOr go another way: I need help with the down payment