
The four main loan types
The short version
Most home loans are one of four types. They differ in down payment, credit, mortgage insurance and who can use them.
| Loan | Minimum down | Mortgage insurance | Often fits |
|---|---|---|---|
| Conventional | 3% first-time, 5% otherwise | Monthly under 20% down, and it can be removed later | Stronger credit, or 20% down to avoid insurance |
| FHA | 3.5% | 1.75% upfront plus a yearly premium | Lower scores or higher debts |
| VA | None | None; a one-time funding fee instead | Eligible veterans, service members and some surviving spouses. Often the best choice for those who qualify |
| USDA | None | 1% upfront plus 0.35% a year | Eligible rural areas, within income limits |
If you qualify for a VA loan, start there. It is often the best of the four, with no down payment, no monthly mortgage insurance and typically the lowest rate. Otherwise, the right fit depends on your credit, your savings and the home's location, which is why seeing the options side by side matters.
Homes on a few acres are common in Southwest Colorado and work with all four loan types when the appraisal supports them. Many rural addresses here fall in USDA-eligible areas, so check the map before you rule USDA out. San Miguel County has a higher conforming limit, $994,750, than the rest of our region.
Go deeper
Conventional
Conventional loans follow Fannie Mae and Freddie Mac rules. They are the most common type and work for homes you live in, second homes and rentals.
- Loan limit: $832,750 for one unit in most of Colorado. Larger loans are jumbo loans, with their own rules.
- Mortgage insurance: priced by your score and down payment. You can ask to remove it at 80% of the original value, and it ends automatically at 78%.
- HomeReady and Home Possible: 3% down and reduced mortgage insurance for incomes up to 80% of the area median.
- Debt ratio: up to about 50% with automated approval.
FHA
- Credit: 3.5% down from a 580 score, or 10% down from 500 to 579.
- Mortgage insurance: 1.75% upfront, usually added to the loan, plus a yearly premium of 0.55% with less than 5% down or 0.5% with 5% or more, for most loans. It lasts the life of the loan with less than 10% down, or 11 years with 10% or more.
- Limits: start at $541,287 for one unit and run higher in costlier counties.
- Who and what: homes you will live in, one to four units, for U.S. citizens and permanent residents. Non-permanent residents have not been eligible since May 2025.
Many FHA borrowers later refinance into a conventional loan once they have enough equity, to remove the insurance.
VA and USDA
VA: If you qualify, a VA loan is often the best option. It requires nothing down with full entitlement, has no monthly mortgage insurance and typically has the lowest rate of the four. The one-time funding fee is 2.15% on a first use with less than 5% down, and veterans who receive VA disability compensation pay none. More on VA loans.
USDA: No down payment is required for homes in eligible rural areas when household income is within 115% of the area median. The yearly fee lasts the life of the loan. More on USDA loans.
Both are for homes you will live in, and both require the home to meet basic safety and condition standards.
Beyond the four main types
- Jumbo loans go above the conforming limit. Rules vary by lender, and they often require more down and more reserves.
- Bank statement loans qualify self-employed borrowers on deposits instead of tax returns. See buying when you are self-employed.
- DSCR loans qualify rental property on its rent. See DSCR loans.
- Renovation loans add repair money to a purchase. See renovation loans.
Most of these cost more than the four main types, so they usually make sense when none of those four fits.
See it with your numbers
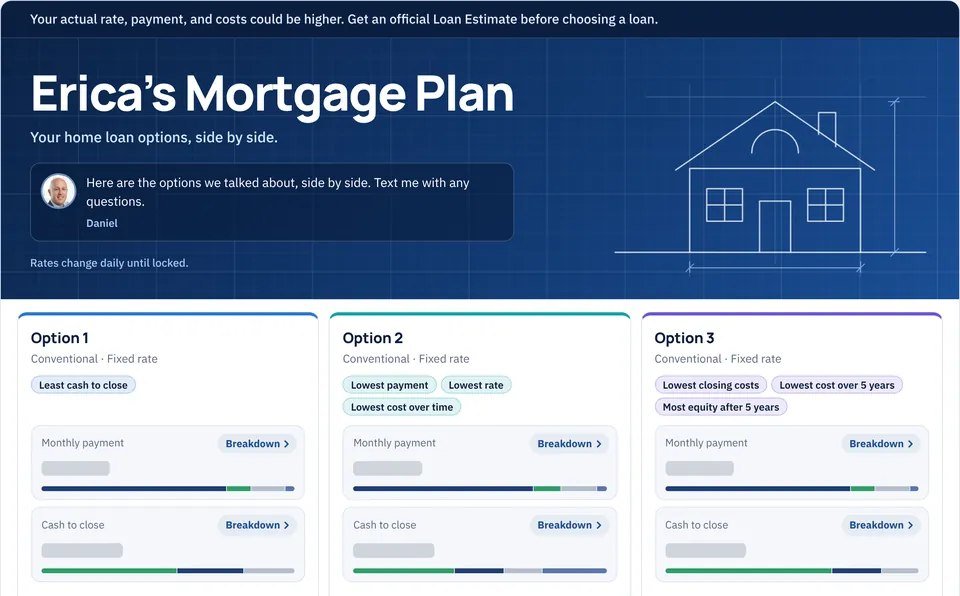
Your Mortgage Plan puts the loan types you qualify for side by side as Option 1, Option 2 and so on, with the payment and cash to close for each.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Lesson 2 of 7 in What can I get?Why VA loans usually win, and who qualifiesIf you qualify for a VA loan, it is often your best option: no down payment, no monthly mortgage insurance and typically lower rates than other loans.Read the lessonOr go another way: I am buying outside townI am self-employed