
Down payment assistance: what it really costs
The short version
Down payment assistance can help you buy sooner, but it is rarely free. Most assistance is a loan, secured by a second lien on your home and repaid when you sell or refinance; only some is a grant. Even a grant usually has a cost, because the first mortgage that comes with it often carries a higher rate than the same loan without assistance.
- CHFA grant: up to 3% of your first mortgage, capped at $25,000. There is nothing to repay.
- CHFA second mortgage: up to 4%, capped at $25,000. There is no monthly payment, but it is due when you sell, refinance or pay off the first loan.
- Local programs such as HomesFund: down payment loans for buyers in Montezuma, La Plata, Archuleta, Dolores and San Juan counties, secured by a lien on the home.
- Gifts from family: often the least expensive help available.
What matters most is how much more you will pay each month, what you will owe when you sell or refinance, and how long until that adds up to more than the help. We show you each option with and without assistance before you apply.
In Southwest Colorado, assistance comes mainly from CHFA and from HomesFund in Durango. CHFA's income and purchase price limits vary by county, and some limits in our counties are lower than the statewide figure. Before you apply for either, we price your loan with and without the assistance so you can see the difference.
Go deeper
CHFA's rules
- Assistance pairs only with a CHFA first mortgage, made through a CHFA participating lender.
- A middle credit score of 620 or higher.
- Combined borrower income up to $178,920 for most programs. Some programs, and some counties, have lower income and price limits.
- At least $1,000 of your own money toward the purchase.
- Every borrower completes a CHFA-approved homebuyer class.
- First-time and repeat buyers can both use it. Buyers with a permanent disability and first-generation buyers may qualify for up to $25,000 regardless of loan size.
The second mortgage also comes due if the home stops being your main residence.
Doing the math
Put the help and its cost side by side. For example, suppose assistance gives you $10,000, and the loan that comes with it costs $60 more a month than the loan you would get without it.
$10,000 ÷ $60 = about 167 months, or almost 14 years.
If you expect to keep the loan longer than that, the extra payments add up to more than the help. A second mortgage is repaid when you sell or refinance, so any future refinance also means paying it off.
It is also worth comparing assistance with waiting. If you could save the same amount in a year or two, the less expensive loan may be worth the wait. If prices or rents are rising, buying sooner may matter more.
HomesFund
HomesFund, based in Durango, offers down payment loans to buyers in Southwest Colorado. We compare your options with and without them before anyone applies.
Its shared appreciation loans have no monthly payment. Instead, HomesFund receives a share of the home's future rise in value, in proportion to the help it provided. It is a loan secured by a lien on your home, not a gift. It costs little if values stay flat and more if they climb, so weigh what you would give up later against what you receive now.
Eligibility, income limits and areas served change, and we confirm the current terms when we compare your options.
Gifts and other help
- Gifts from family can cover the whole down payment on a conventional loan for a one-unit home you will live in, with a signed gift letter and a paper trail. See how much you need saved.
- Seller credits can pay closing costs up to program limits, though not the down payment.
- Lender credits trade a higher rate for help with costs. Weigh them the same way as assistance.
- Employer help: some employers offer assistance, so it is worth asking your HR office.
See it with your numbers
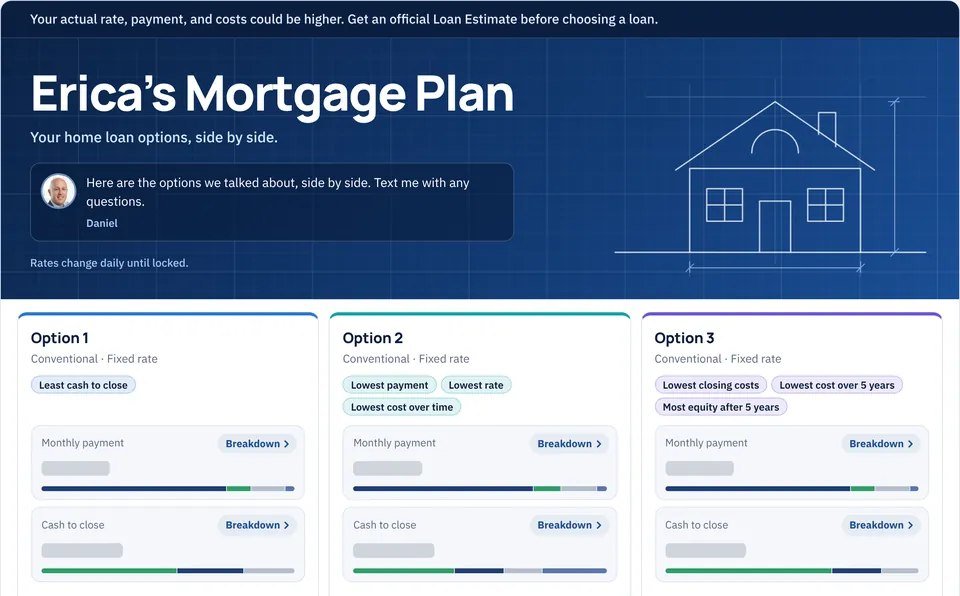
Your Mortgage Plan can show an option with assistance next to one without, so you can compare cash to close, the payment and cost over time.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Stage 3: Shopping smartGetting pre-approvedA mortgage pre-approval means a lender has checked your credit, income and assets. It backs your offer, but it is not a loan commitment.Read the lessonOr go another way: Back to how much I need savedContinue in order: Buying when you are self-employed