
How we work
From a first conversation to closing, in ten steps
Two calls get you to your Mortgage Plan: a short first conversation, then a second call to go through it together. After that, clear steps, honest timing and one person who knows your file from start to finish.
Your plan
Step 1: A first conversationPurchase
You start here
It starts with a conversation by phone, video or in person. The short request form is one way to set it up. Tell him what you want to do and when; ranges and estimates are fine.
Phone, video or in person
Your plan
Step 1: Start your Ownership PlanRefinance
You start here
A refinance can start with a free Ownership Plan, set up on your own. We email you a link to confirm it is you, you answer about two minutes of quick questions about your home and loan, and it builds itself. It follows your home’s value, your equity and your rate against the market. There is no cost and no obligation.
Prefer to start with a quote? Answer a few questions about your home and loan, and Daniel reviews them, reaches out and prepares your options in a free Ownership Plan. Ask for a quote.
A few minutes, on your own
Step 2: Daniel builds your planPurchase
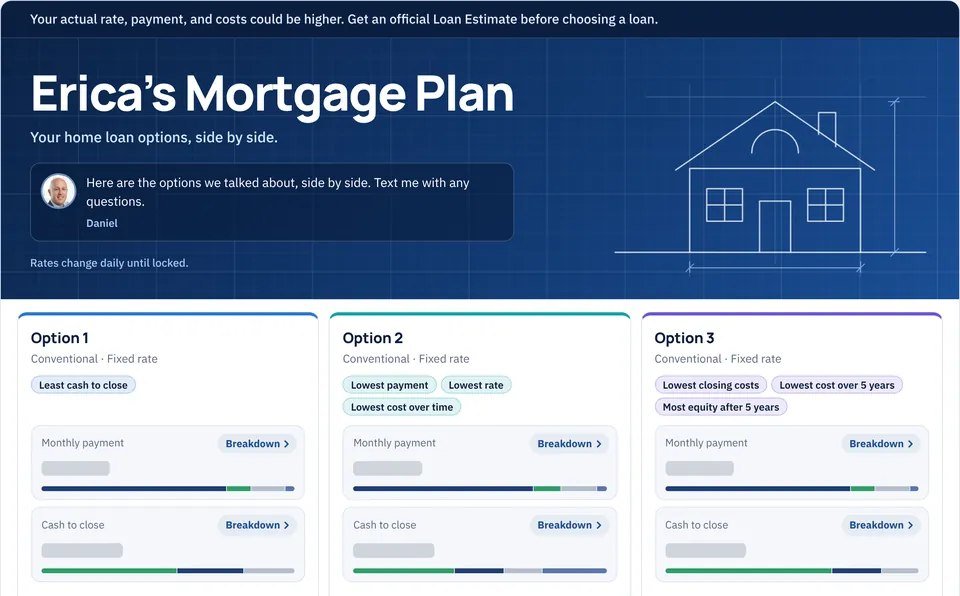
Daniel builds your Mortgage Plan from that conversation. It shows the options that fit you, side by side: the payment, the cash to close and the cost over time.
After your conversation
Step 2: Request a quoteRefinance
When you want to explore a refinance, tap Request a quote inside your Ownership Plan. Daniel prepares current refinance options there, each set beside your current loan.
Whenever you are ready
Step 3: A second callPurchase
When your plan is ready, we schedule a second call, by phone, video or in person. We look forward to speaking with you soon.
When your plan is ready
Step 3: Book your callRefinance
The booking page opens as you ask, so your call is set while Daniel prepares your options. By phone, video or in person.
As you ask
Step 4: We go through it together
Daniel sends your Mortgage Plan right before that call, and you go through it together on the call: the trade-offs between the options, what is realistic and what comes next. It stays with you afterward.
You go through the options together on that call: the payment, the cash to close and the month you would break even.
When you are ready to move forward, we talk through your credit and order a report with your permission when one is needed, and the numbers firm up.
With your documents in, we issue a pre-approval letter, so your offer is taken seriously.
About 20 to 30 minutes
Finding your home
Step 5: You shop for a homePurchase
You shop with a clear budget, and we support you along the way: we run the numbers on homes you are considering, tell you what a well, septic, acreage or HOA dues mean for your loan, and update your Mortgage Plan when your plans change.
Ready to make an offer? Tap “I’m about to make an offer” in your Mortgage Plan. Daniel confirms the numbers, usually within an hour, and your signed pre-approval letter opens on your plan. From there you share it with your agent, who sees your maximum price and the numbers for the contract.
As long as you need
Your refinance
Step 5: You choose your optionRefinance
Your plan sets each refinance option beside your current loan: the payment, the cash to close, the month you break even and the cost over time. When one makes sense for you, you decide to move forward. If none does, we say so.
When the numbers work
Step 6: You are under contractPurchase
Send us your contract the day it is signed. We gather what your loan needs, such as recent pay stubs and bank statements, and set the timeline around your contract’s dates.
Anyone can confirm your pre-approval letter is real with the code on it, at plan.montezumamortgage.com/verify.
Offer accepted
Step 6: We gather your detailsRefinance
We gather your documents and your current loan’s details: your latest mortgage statement, your homeowners insurance, and recent pay stubs and bank statements.
Documents in
Your loan
Step 7: Loan setup and lock
We finalize your loan application, and the lender sends your Loan Estimate within three business days of your application. We go through it with you line by line and match it to your Mortgage Plan. Nothing is charged before you have your Loan Estimate and decide to proceed.
Then you decide to lock or float. A lock is possible once there is an accepted contract on the home, your documents are in, credit has been pulled, and the loan is structured and approved through automated underwriting.
Then you decide to lock or float. A lock is possible once your documents are in, credit has been pulled, and the loan is structured and approved through automated underwriting; a refinance needs no contract.
Rates move every day, both ways, and no one can predict them. When you are ready and the numbers look right, you lock.
Loan Estimate within three business days
Step 8: Processing
We submit your file to the lender’s underwriter and order title. Once you are through your inspections, we order the appraisal, if your loan needs one, through the lender’s appraisal management company (for a VA loan, VA assigns the appraiser).
We submit your file to the lender’s underwriter, order title and your current loan’s payoff, and order the appraisal, if your loan needs one, through the lender’s appraisal management company (for a VA loan, VA assigns the appraiser).
We clear the underwriter’s conditions, confirm your new homeowners insurance and keep you posted until your loan is clear to close.
We clear the underwriter’s conditions, confirm your homeowners insurance and keep you posted until your loan is clear to close.
For rural homes with a well or septic, we tell you early which tests your loan needs.
About 2 to 4 weeks
Step 9: Clear to close
Final approval. The lender prepares your closing package of loan documents and sends your Closing Disclosure, which you receive at least three business days before closing. We go through it with you line by line and match it to your Mortgage Plan.
3+ business days before closing
Closing
Step 10: Closing
You sign your papers and get your keys.
You sign your papers, and your new loan pays off the old one. When you refinance your primary home with a new lender, federal law gives you until midnight of the third business day after the latest of closing, receiving the notice of your right to cancel and receiving the required disclosures, so the loan funds after that. A refinance of a second home or rental has no such wait, and one with your current lender may have it only on new money borrowed. Then your new loan takes over: the lower rate, or the cash you planned for.
If you bring money to closing, call the title company before you wire it, at a number you know is right, from us, your agent or the title company’s own website, never one from an email or text.
If you bring money to closing, call the title company before you wire it, at a number you know is right, from us or the title company’s own website, never one from an email or text.
At closing, your Mortgage Plan becomes your Ownership Plan. It follows your home’s value and your equity, and when you want a refinance quote, you tap Request a quote inside it. See what is in the Ownership Plan.
About 30 to 45 days from an accepted offerFunds after any waiting period
What to have ready
- Pay stubs for the last 30 days
- W-2s for the last two years
- Two years of tax returns if you are self-employed or have rental or other income
- Two months of bank and retirement statements, all pages
- A photo ID
- For a refinance, your latest mortgage statement and your homeowners insurance
- For VA loans, nothing extra: we request your Certificate of Eligibility for you
We will tell you if your situation requires anything else. Please do not email account numbers or Social Security numbers. We will give you a secure way to send documents.
Until you close
- Keep your employment steady, or tell us first about any change
- Avoid opening new credit or financing furniture
- Avoid moving large sums without a paper trail
- Before you send money, confirm the wire instructions: call the title company at a number you know is right, from us, your agent or the title company’s own website, never one from an email or text, and call Daniel
If you are new to the process, the first home path walks through each step in more detail.
Take the first step
It starts with a conversation. Send a short request, or book a time to talk.