
Between approval and funding
The short version
An approval is not final until the loan funds. Lenders check again right before closing, re-verifying your job within days of signing and watching for new debt. Until the loan funds, keep the following in mind:
- Keep your job steady. Talk to us before you change jobs, switch to commission pay or become self-employed.
- Do not open new credit. Avoid car loans, new cards and furniture financing, and do not co-sign for anyone.
- Leave your money where it is. Large deposits need a paper trail, and every transfer between accounts is one more thing to document.
- Keep paying everything on time, including rent or your current mortgage.
It is also important to protect your cash to close. Criminals send fake wiring instructions that appear to come from your title company or agent. We will never change wire instructions by email. Before you wire any money, call the title company at the number on your contract, not one from an email or text, and confirm the account details.
Go deeper
What lenders re-check
Your job. On loans that follow Fannie Mae's rules, the lender must verify your employment within 10 business days before closing, or within 120 days if you are self-employed.
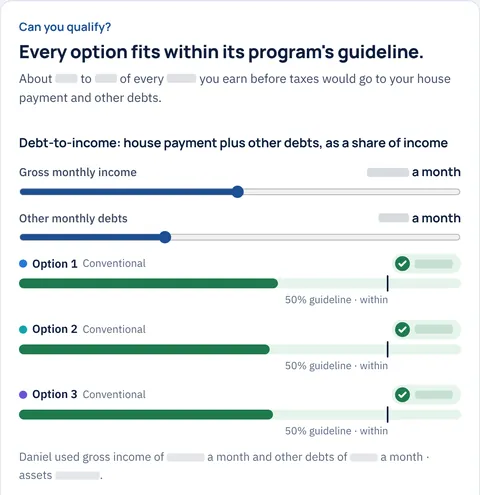
Your credit. Lenders may check your credit again or watch for new accounts. A new car payment raises your debt-to-income ratio and can undo an approval. A lower score can change your pricing.
Your documents. Pay stubs, statements and credit reports become outdated. If closing is delayed, expect to send newer ones.
If something changes, tell us right away. Changes are easier to work through when we hear about them early.
Wire fraud: a safe routine
- Early on, pick two trusted contacts, such as your agent and your title officer, and talk through how closing funds will move by phone or in person.
- Before sending money, call the title company at the number on your contract and confirm the account name and number.
- Treat any change in instructions as a warning sign, however urgent or official it looks.
- Do not email account numbers or other financial details.
- After you send, call to confirm the money arrived.
If something goes wrong, call your bank right away and ask it to recall the wire, then report it to the FBI at ic3.gov. Speed matters.
Closing and funding
On a purchase, you sign, the lender sends the loan money to the title company, the deed records, and the seller is paid. Your keys come at the possession date and time in your contract.
A refinance of the home you live in works differently. You have until midnight of the third business day after signing to cancel, and Saturdays count. The loan does not fund, and your old loan is not paid off, until that window passes. Purchase loans do not have this right to cancel.
See it with your numbers
Your Mortgage Plan shows your qualifying ratios (DTI), so you can see how a new car payment or card balance would affect your approval.
Already have a Mortgage Plan? Open your link, or text Daniel.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Stage 6: OwningYour first year as an ownerYour mortgage payment can change even with a fixed rate, because escrow covers taxes and insurance. A yearly escrow analysis resets it.Read the lessonOr go another way: I want to remove mortgage insurance