
Inspections, and what to do with them
The short version
An inspection tells you what you are buying. It is separate from the appraisal, which is about value. Schedule it the day your offer is accepted, because the deadline to object comes quickly.
- General home inspection: roof, structure, heating, plumbing, electrical and drainage.
- Radon: common in Colorado and inexpensive to test.
- Well: water quality and flow.
- Septic: pumped and inspected by a certified inspector.
- Sewer scope: a camera inspection of the sewer line, for older homes on town sewer.
- Specialists when something is flagged: a structural engineer for cracks or movement, a roofer, a chimney sweep for a wood stove.
Then sort the findings into three groups: safety and systems, costly repairs coming soon, and normal wear. The first two are worth negotiating. The last is part of owning a home.
Rural homes in Southwest Colorado usually need more than a general inspection. Plan for a well test, a septic inspection, and a review of the propane tank (owned or leased), the wood stove and the chimney. La Plata and Archuleta counties require a septic inspection for most sales, and Montezuma County requires one in some cases. Schedule early, because snow and frozen ground can delay septic work in winter.
Go deeper
Radon and foundations
Radon is an invisible gas that comes from the ground. The EPA recommends fixing a home at 4 pCi/L or higher and considering a fix between 2 and 4. A short test during your inspection period shows where the home stands. If the level is high, a mitigation system is a common, well-understood solution and a reasonable item to negotiate.
The Colorado Geological Survey describes swelling soil as a common problem that can seriously damage houses, often slowly. Doors that stick, sloping floors and stair-step cracks in block or drywall are reasons to bring in a structural engineer before your objection deadline.
Wildfire risk and insurance
The Colorado State Forest Service divides the land around a home into zones: the first 5 feet kept free of anything that burns, fuels reduced out to 30 feet, and fuels managed out to about 100 feet. A Class A roof, screened vents and clear gutters also matter.
Request an insurance quote early, before your property insurance deadline. If standard insurers decline a home, Colorado's FAIR Plan is a last resort after three declinations. Its coverage is narrower, pays actual cash value rather than replacement cost, and is capped at $750,000 for a home and its contents. Lenders require proof of coverage before closing.
Using the results
You have four options: ask for repairs, ask for a credit, ask for a lower price, or cancel the contract within your deadline.
For FHA, VA and USDA loans, the appraiser can require health and safety items to be fixed before closing, so those items usually need repairs rather than credits. Cosmetic and wear items are easier to resolve with a credit or a lower price.
In Colorado, you send objections by the Inspection Objection Deadline and resolve them by the Inspection Resolution Deadline. If you and the seller do not reach agreement in time, the contract states what happens next. Read that section before you send your list.
See it with your numbers
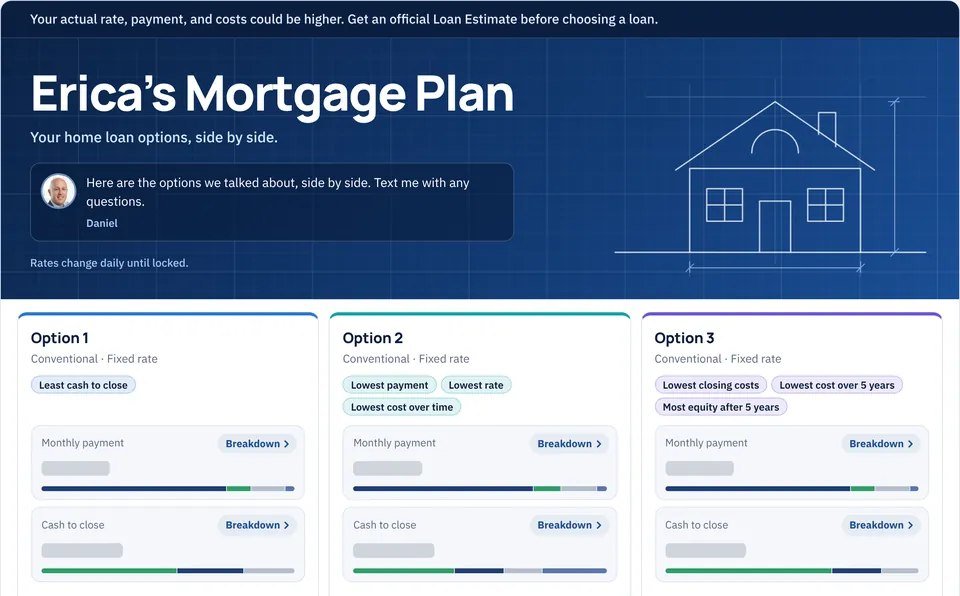
If repairs turn into a credit or a price change, your Mortgage Plan shows how the payment and cash to close move for each option.
Already have a Mortgage Plan? Open your link, or text Daniel.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Lesson 4 of 9 in Finding the homeAppraisals and low valuesA home appraisal confirms the value supports your price, and your loan is based on the lower of the two. A low value still leaves you options.Read the lessonOr go another way: It has a well or septicIt needs more work than I expected
Sources
- EPA: health risk of radon
- Colorado Department of Public Health and Environment: radon
- Colorado Geological Survey: swelling soils
- Colorado State Forest Service: protect your home from wildfire
- Colorado Division of Real Estate: the FAIR Plan
- La Plata County Public Health: septic Continued Use Permit guide
- Archuleta County: septic transfer of title